What open enrollment is and why the timing matters
Open enrollment is the period each year when you can sign up for, change, or drop a health insurance plan. Outside this window, insurers are generally not required to accept new applicants or process plan changes. That restriction exists because allowing year-round enrollment would let people sign up only when they got sick, which would destabilize the insurance pool for everyone.
Understanding which type of coverage you have determines which enrollment calendar applies to you. The three main systems each run on their own schedule:
- ACA Marketplace plans: The federal open enrollment period generally runs November 1 through January 15, though some states that run their own exchanges set different end dates. Coverage starting January 1 requires enrollment by December 15 in most cases.
- Employer-sponsored plans: Each employer sets its own window, typically in the fall, lasting two to four weeks. Check your HR portal or benefits guide for exact dates.
- Medicare: The Annual Enrollment Period (AEP) runs October 15 through December 7. This is separate from the Initial Enrollment Period, which applies when you first become eligible. See our Medicare enrollment checklist for a full breakdown of documents and deadlines.
Missing any of these windows does not automatically mean you are without options, but it does narrow them significantly.
This article is for general informational purposes only and is not personalized insurance, financial, or legal advice. Coverage terms, dates, and eligibility vary by plan, employer, and state. Consult a licensed insurance agent or benefits adviser for guidance specific to your situation.
How to prepare before the window opens
Rushing a plan decision in the final days of open enrollment is one of the most common reasons people end up with coverage that does not fit their needs. The steps below walk you through preparation so you enter the window ready to compare and decide.
Review your current plan's renewal notice
Insurers send renewal or change notices before open enrollment begins. Read it carefully: premiums, deductibles, and drug formularies can change from year to year even if you do nothing. Note any changes that affect care you expect to use.
List your expected healthcare needs for the coming year
Consider any planned procedures, ongoing prescriptions, and providers you want to keep. Check whether those providers are in-network on any plan you are considering. A plan with a lower premium can cost more overall if your preferred doctors are out of network.
Gather the documents you will need to enroll
Having the right information on hand prevents last-minute delays. You will typically need:
- Social Security numbers for yourself and any dependents you are enrolling
- Proof of current coverage (if transitioning from another plan)
- Recent pay stubs or income documentation if applying for subsidies on the Marketplace
- Medicare cards if you or a dependent is enrolled in any part of Medicare
Compare at least two plans side by side
Use the Summary of Benefits and Coverage (SBC) for each plan you are considering. The SBC is a standardized document that makes it easier to compare what you pay for common services. Focus on the deductible (the amount you pay before insurance kicks in), the out-of-pocket maximum (the most you would pay in a year), copays for primary care and specialist visits, and whether your prescriptions are covered.
Submit your enrollment before the deadline
Do not wait until the final day. Technical problems and high traffic on enrollment platforms are common at the end of the window. Submit your application with enough time to resolve any issues. After enrolling, save or print your confirmation and verify that you receive a member ID card before your coverage start date.
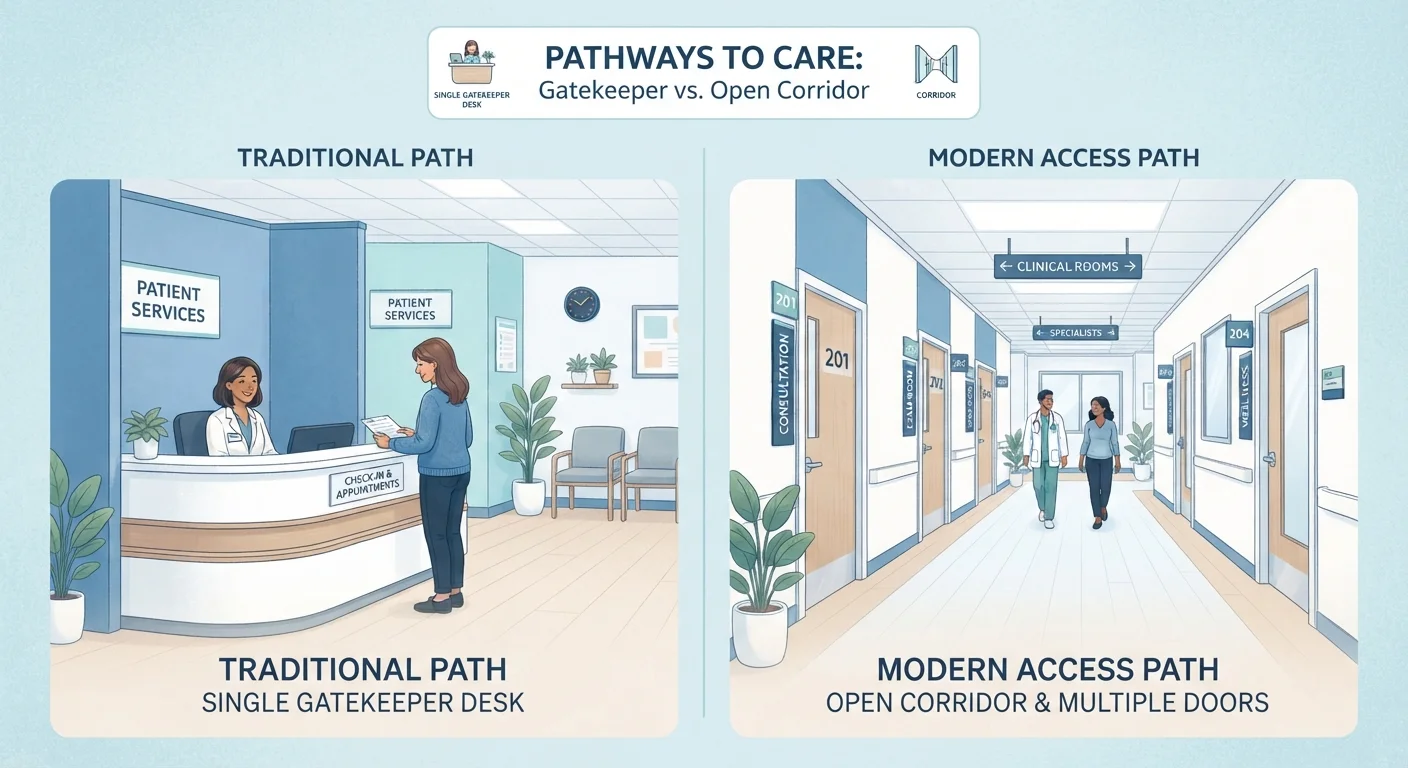
Before you compare plans, it helps to know what kind of plan structure suits your care habits. Our guide to HMO vs. PPO differences explains how network restrictions and referral requirements affect both cost and convenience. Separately, if you are approaching 65, review how Medicare and Marketplace coverage differ after 65 before assuming your current plan is still the right one.
Set a calendar reminder now
Open enrollment windows are short, and they open on the same dates each year for most programs. Adding a reminder for late October gives you time to gather documents and review plan options before the window opens. Employers often send benefits guides in September or October, so watch for those too.
What to do if you miss open enrollment
Missing the window is stressful, but several legitimate paths may still be available depending on your circumstances.
Special Enrollment Periods (SEPs)
A Special Enrollment Period lets you enroll or make changes outside the standard window if you experience a qualifying life event. Common qualifying events include:
- Losing job-based coverage (including COBRA expiration)
- Getting married, divorced, or having a child
- Moving to a new coverage area
- Gaining or losing eligibility for Medicaid or CHIP
For ACA Marketplace plans, you generally have 60 days from the qualifying event to enroll. Documentation is required, so gather proof of the event promptly.
Medicaid and CHIP
Medicaid and the Children's Health Insurance Program (CHIP) have no enrollment window. If your income qualifies, you can apply any time of year through your state's Medicaid agency or HealthCare.gov.
Short-term plans
Short-term health plans are available outside of open enrollment in many states, but they are not required to cover the same benefits as ACA-compliant plans and can exclude pre-existing conditions. They are a stopgap, not a replacement for comprehensive coverage.
Medicare late enrollment
For Medicare specifically, missing your Initial Enrollment Period can trigger permanent premium surcharges on Part B and Part D. How late enrollment penalties work covers the exact calculations and the limited exceptions that allow penalty waivers.
Before committing to any plan, work through the checklist of questions to answer before picking a health plan to make sure the coverage structure matches your actual needs.
Missed Medicare deadlines carry lasting costs
Unlike ACA Marketplace plans, Medicare late enrollment penalties are permanent and added to your monthly premium for as long as you have coverage. A late Part B penalty, for example, is calculated as a percentage increase for each 12-month period you were eligible but did not enroll. Exceptions are narrow and require documentation. If you are nearing 65, confirm your enrollment timeline well in advance.