What this checklist covers
Medicare enrollment does not happen automatically for most people. Unless you already receive Social Security retirement benefits before turning 65, you must actively sign up. This checklist walks through the documents to gather, the deadlines to track, and the coverage decisions to make before you submit your application.
If you are also weighing how Medicare compares to other coverage options, this overview of Medicare versus Marketplace plans explains the differences and how to time your transition without creating a gap in coverage.
ssa.gov account
Review your earnings history, confirm Medicare tax contributions, and submit your Medicare application online.
medicare.gov Plan Finder
Compare Part D drug plans and Medicare Advantage options using your actual medication list and zip code.
State Health Insurance Assistance Program (SHIP)
Connect with a free, unbiased local counselor who can walk through your enrollment options without selling you a plan.
Current insurance policy documents
Confirm your coverage end date and creditable coverage status before your enrollment window closes.
Social Security earnings statement
Verify your Medicare tax history to confirm Part A premium-free eligibility.
Documents and information to gather first
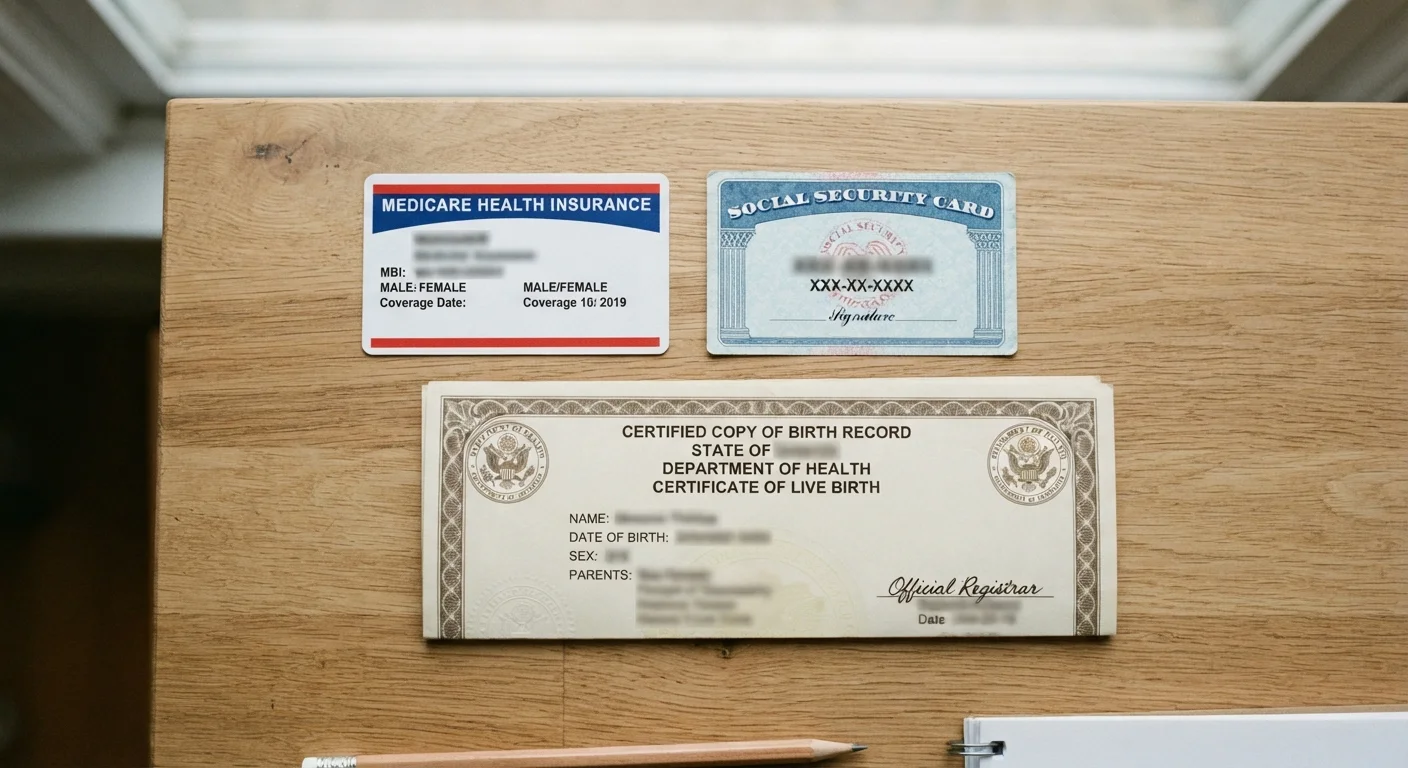
Having the right paperwork ready before you contact Social Security will speed up your application significantly. Delays most often happen when an applicant cannot provide verification of age, citizenship, or prior insurance.
Personal identification
Work and insurance history
Current health coverage
Prescription and provider review
Financial and benefit coordination
Application logistics
Your work history matters because Medicare Part A (hospital insurance) is generally premium-free if you or your spouse paid Medicare taxes for at least 10 years. If you are unsure of your record, you can review your earnings history through your Social Security account at ssa.gov.
For a broader look at how Social Security and Medicare interact, this beginner's roadmap to Social Security benefits covers the connection between the two programs.
Enrollment windows and deadlines
Medicare has several distinct enrollment periods, and the one that applies to you depends on your situation at age 65.
Initial Enrollment Period (IEP): A seven-month window that begins three months before the month you turn 65, includes your birth month, and ends three months after. This is the standard window for most people.
Special Enrollment Period (SEP): If you are covered by employer-sponsored insurance through your own or a spouse's current job at 65, you may qualify for an SEP to enroll later without penalty. Coverage from a former employer or COBRA does not qualify.
General Enrollment Period: If you miss your IEP and do not qualify for an SEP, you can enroll January 1 through March 31 each year, but coverage does not begin until July 1 and late-enrollment penalties may apply.
Permanent premium surcharges for late enrollment can add up to a meaningful annual cost, so confirming your window early matters. You can also review how open enrollment periods work more broadly to understand the wider calendar.
Missing your window has lasting consequences
Late enrollment in Part B adds a 10 percent surcharge to your premium for each full 12-month period you were eligible but did not enroll. Part D carries a similar penalty calculated monthly. Both surcharges are permanent and added to your premium for as long as you have that coverage. Read how these penalties are calculated before assuming you can wait.
Coverage decisions before you enroll
Original Medicare includes Part A and Part B, but most people also need to decide on Part D (prescription drug coverage) and whether to add a Medicare Supplement (Medigap) plan or switch to a Medicare Advantage plan (Part C).
Making these choices without comparing your actual prescriptions, preferred doctors, and expected care needs can lead to mismatched coverage. This checklist of questions to work through before picking a health plan applies directly to Medicare decisions.
If your income is limited, Medicaid may work alongside Medicare to cover costs such as premiums, copays, or long-term care. How income and asset rules work for senior Medicaid eligibility explains the general framework.
COBRA and retiree coverage do not protect you
If you leave a job and continue coverage through COBRA or a retiree health plan, that coverage does not qualify as the employer-sponsored insurance needed to trigger a Special Enrollment Period. The clock on your Initial Enrollment Period continues to run. Confirm your coverage type with your plan administrator before assuming you are protected from penalties.
This article is for general informational purposes only and is not a substitute for advice from a licensed insurance counselor, Medicare advisor, or qualified benefits specialist. Coverage rules, deadlines, and eligibility conditions change; verify current details at medicare.gov or by calling 1-800-MEDICARE before making enrollment decisions.