Why the premium is not the whole picture
When shopping for health coverage, the monthly premium is the number that appears first. It is easy to compare because it is a single, recurring figure. But two plans with identical premiums can expose you to very different costs once you actually use care.
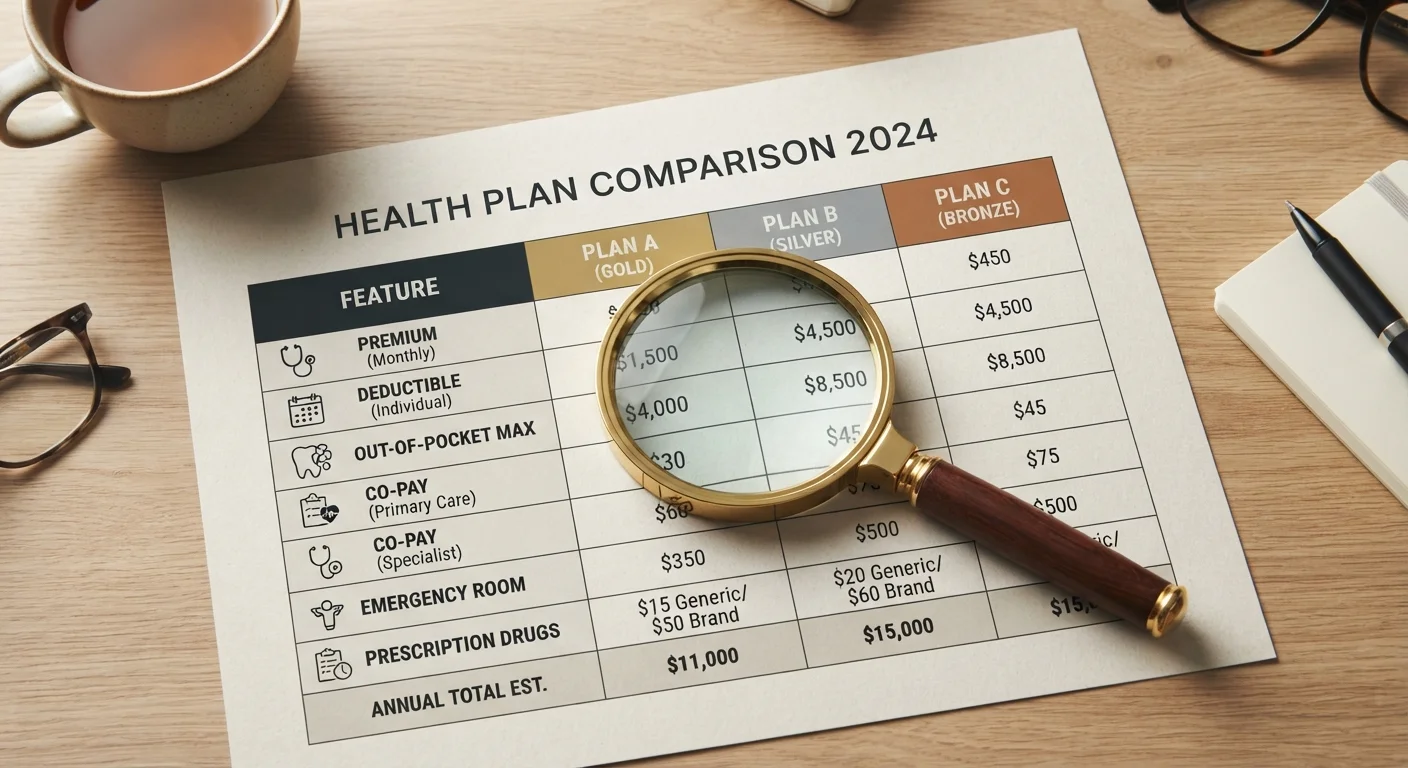
Three cost-sharing terms shape what you pay at the point of care. The deductible is the amount you pay out of pocket before your insurer begins sharing costs. The copay is a fixed fee for a specific service, such as a primary care visit. The out-of-pocket maximum is the annual ceiling on your cost-sharing; once you hit it, the plan covers 100 percent of covered in-network services for the rest of the year. Understanding how these three interact helps you estimate your real annual exposure, not just your monthly bill.
A plan with a low premium and a $7,000 deductible can cost far more than a plan with a higher premium and a $1,500 deductible if you need surgery, have a chronic condition, or simply use care regularly.
Network breadth and plan type
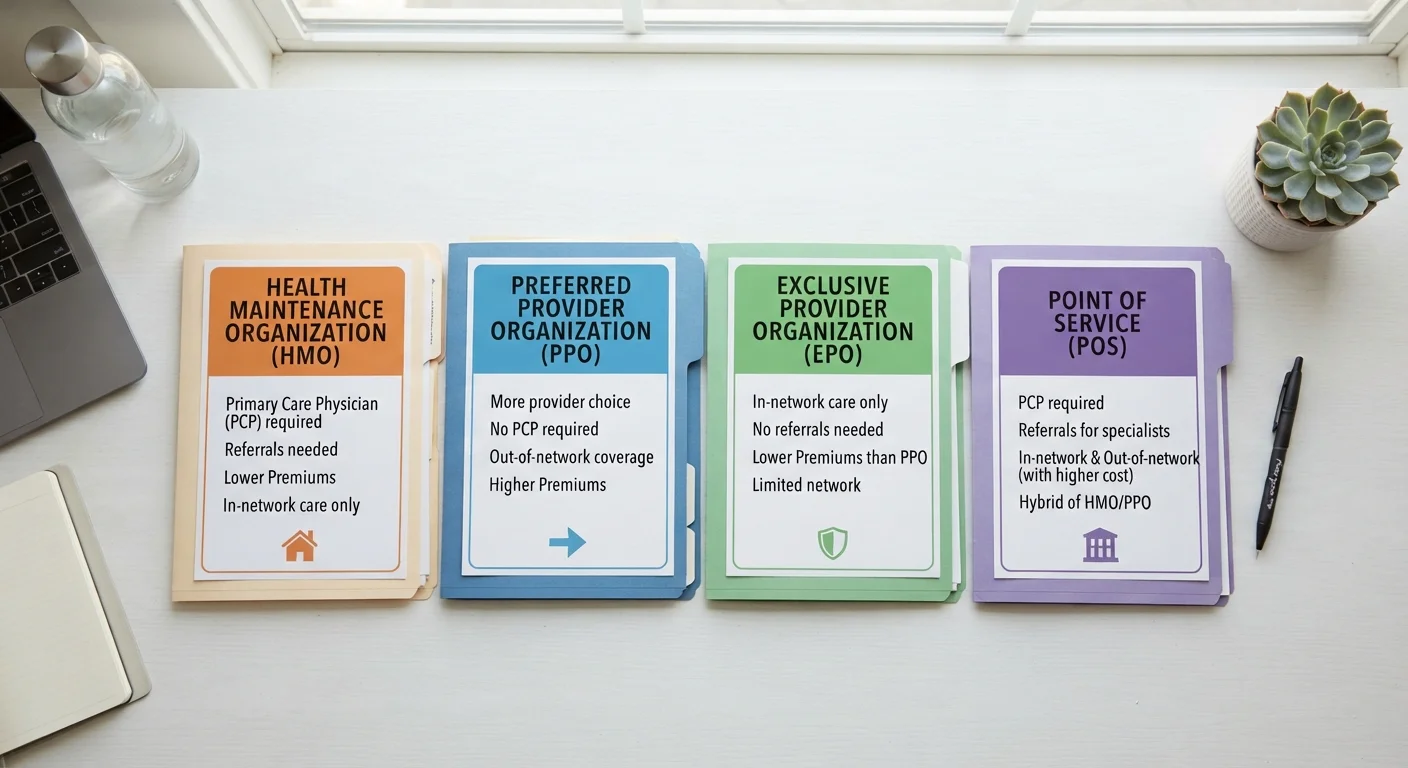
Every plan restricts or prices care based on whether a provider is inside its network. The plan type determines how strict that restriction is.
- An HMO (Health Maintenance Organization) requires you to use in-network providers and get referrals from a primary care physician to see specialists. Out-of-network care is generally not covered except in emergencies.
- A PPO (Preferred Provider Organization) lets you see out-of-network providers at a higher cost-share, and you do not need referrals. That flexibility comes with higher premiums.
- An EPO (Exclusive Provider Organization) uses a defined network like an HMO but does not require referrals. Go outside the network and you pay the full bill.
- An HDHP (High-Deductible Health Plan) pairs a high deductible with eligibility for a Health Savings Account (HSA), which lets you set aside pre-tax dollars for medical costs.
A detailed breakdown of all four plan types can help you match the structure to how you actually use care. If your current doctors are not in a plan's network, switching could mean paying significantly more or finding new providers.
The drug formulary: often overlooked, often costly
A formulary is a plan's list of covered prescription drugs, organized into tiers. Tier 1 drugs are usually generics with low copays. Higher tiers, which include brand-name and specialty medications, carry higher cost-sharing. A drug your doctor prescribes may be on one plan's formulary at Tier 2 and another plan's formulary at Tier 4, making the same prescription dramatically different in price depending on which plan you choose.
Before finalizing any plan, look up your current medications in that plan's formulary. Insurers are required to publish formularies, and many allow searches on their websites. Pay attention to whether a drug requires prior authorization, step therapy (trying a cheaper drug first), or quantity limits.
| Factor | What to look at | Why it matters | |
|---|---|---|---|
| Deductible | Annual amount before cost-sharing begins | Amount you owe before the plan pays its share | Higher deductible means more exposure before coverage kicks in |
| Out-of-pocket maximum | Annual cap on your cost-sharing | Limits your total yearly medical spending | Lower cap protects you more if you have a serious illness or injury |
| Network type | HMO, PPO, EPO, or HDHP | Determines which providers you can use affordably | Narrow networks lower premiums but restrict choice |
| Drug formulary | Tier placement of your medications | Sets what you pay per prescription | A drug at Tier 4 can cost hundreds more per fill than Tier 2 |
| Copays and coinsurance | Fixed fee vs. percentage of allowed amount | Your share of each covered service | Coinsurance with a high allowed amount can exceed a flat copay |
Metal tiers on ACA plans and what they signal
If you are shopping on the Affordable Care Act Marketplace, plans are grouped into metal tiers: Bronze, Silver, Gold, and Platinum. These tiers describe how costs are split between you and the insurer across the plan year, not the quality of care. Bronze plans carry lower premiums and higher cost-sharing; Platinum plans carry higher premiums and lower cost-sharing. How each metal tier splits costs is worth reading before you decide.
Silver plans have a specific advantage for people whose income qualifies them for Cost-Sharing Reductions (CSRs): those reductions are only available on Silver plans and can substantially lower deductibles and out-of-pocket maximums. Choosing a Bronze plan to save on premiums may mean giving up that benefit.
Seniors approaching 65 face a separate set of decisions. How Medicare and Marketplace coverage differ after 65 covers what changes when you become eligible, including timing that affects both cost and continuity of care.
Working through a pre-enrollment checklist before you compare plans can help you identify which coverage features matter most for your situation. This article is for general informational purposes and is not a substitute for advice from a licensed insurance professional who can review your specific circumstances.
This article provides general health insurance information for educational purposes only. It is not personalized insurance, financial, or medical advice. Coverage terms, costs, and eligibility vary by plan and provider. Always read plan documents carefully and consult a licensed insurance agent or adviser before enrolling.