How late enrollment penalties work
Medicare penalizes late enrollment in two main parts of the program: Part B (medical insurance) and Part D (prescription drug coverage). These penalties are not one-time fees. They are added permanently to your monthly premium for as long as you have that coverage.
For Part B, the penalty is 10% of the standard Part B premium for each full 12-month period you were eligible but not enrolled. For Part D, the penalty is 1% of the national base beneficiary premium multiplied by the number of months you lacked creditable coverage. Both amounts are recalculated each year as the underlying premium changes, so the dollar impact can grow over time.
Understanding how cost-sharing terms interact can help you see the full picture of what Medicare coverage costs, because penalties affect only the premium side, while deductibles and copays are separate.
The most common enrollment mistakes and how to avoid them
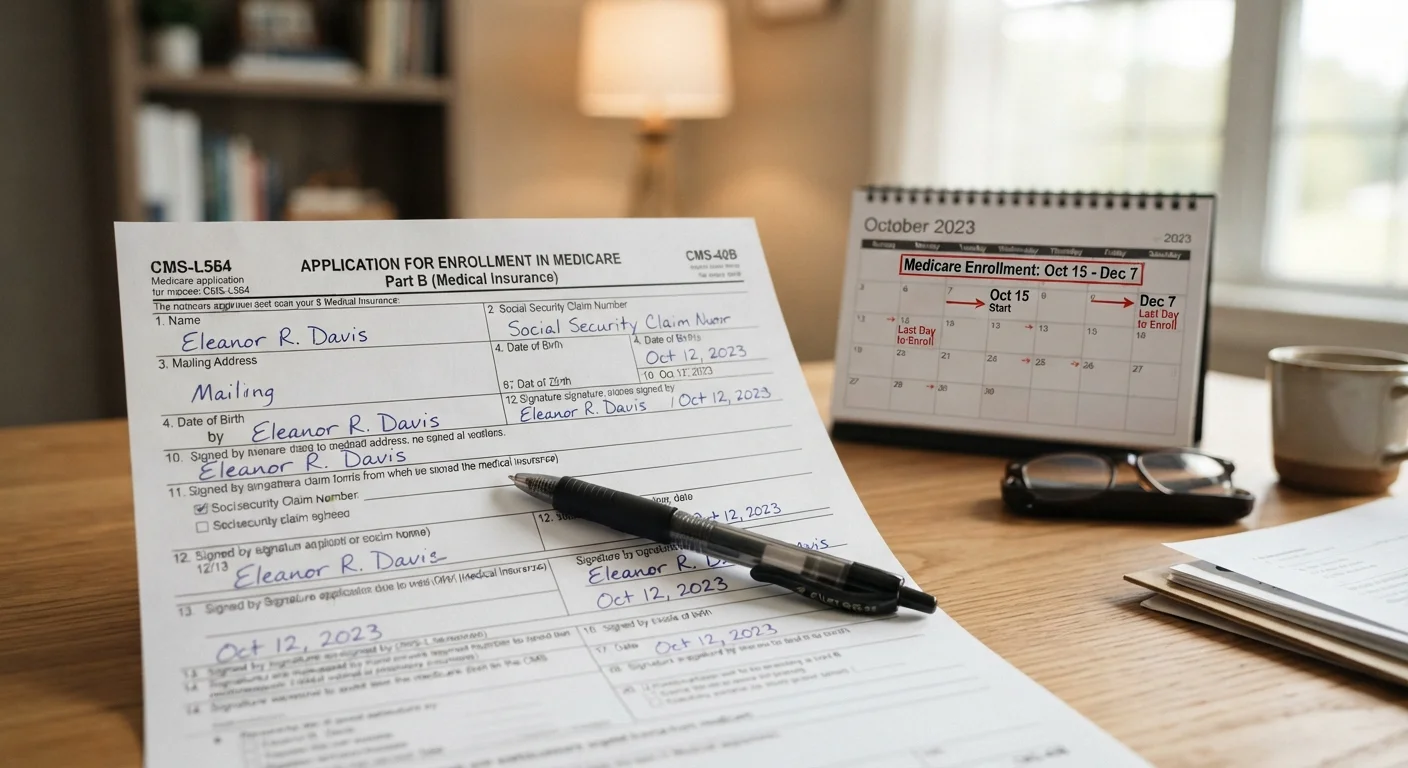
Assuming you have until the end of the year to enroll once you turn 65.
Why it happens: Many people are familiar with annual open enrollment windows for workplace insurance and assume Medicare works the same way.
Believing that retiree coverage or COBRA counts as qualifying employer coverage for a Special Enrollment Period.
Why it happens: The distinction between active employer coverage and post-retirement coverage is not obvious, and many people assume any group health plan qualifies.
Skipping Part D drug coverage because you currently take no prescription medications.
Why it happens: It feels unnecessary to pay for something you are not using, and the monthly premium seems like an avoidable expense.
Waiting to enroll in Part B because you want to keep your Marketplace plan after 65.
Why it happens: People who have come to rely on an ACA Marketplace plan may not realize that staying on it past 65 does not satisfy Medicare's enrollment requirements.
Enrolling late in Part B after leaving an employer plan without verifying the Special Enrollment Period timeline.
Why it happens: People assume they have a generous window after leaving their job to enroll in Medicare, similar to COBRA's 60-day election period.
If you are still comparing coverage types as you approach 65, the factors beyond the monthly premium matter when weighing Medicare plan options alongside any supplemental or drug coverage you may add.
When exceptions apply
A handful of situations do allow late enrollment without a penalty. The most common is an active employer group health plan through your own or your spouse's current employer. If that coverage ends, you qualify for a Special Enrollment Period as described above. Individuals who qualify for the Extra Help (Low Income Subsidy) program can enroll in Part D outside normal windows without penalty. People with end-stage renal disease have separate enrollment rules entirely.
The Social Security Administration and Medicare.gov are the authoritative sources for verifying which exceptions apply to your situation. A licensed State Health Insurance Assistance Program (SHIP) counselor can walk through your specific coverage history at no cost.
Retiree coverage does not protect you
Many people retire with retiree health benefits from a former employer and assume this counts as qualifying coverage for Medicare purposes. It does not. Retiree coverage, COBRA, and ACA Marketplace plans do not grant you a Special Enrollment Period. Enrolling late while relying on any of these plans will result in a permanent Part B penalty. Verify your coverage type with your plan administrator or a SHIP counselor before deciding to delay.
Decisions about when to take Medicare often intersect with Social Security timing. When you start collecting Social Security can affect whether you are automatically enrolled in Medicare Parts A and B, which is a detail worth confirming well before you turn 65.
This article provides general information about Medicare enrollment and is not a substitute for personalized advice. Eligibility rules, penalties, and program details can change. Contact Medicare directly at 1-800-MEDICARE or speak with a licensed SHIP counselor for guidance specific to your situation.