How Social Security retirement benefits work
Social Security is a federal insurance program funded by payroll taxes. When you work and pay into the system, you earn credits toward a retirement benefit. When you stop working and claim, the Social Security Administration (SSA) pays you a monthly amount based on your past earnings.
The program does not draw from a personal savings account in your name. Your taxes fund current beneficiaries, and future workers fund yours. This is why your earnings history, not your contributions, determines what you receive.
Full retirement age (FRA)
The age at which you qualify for your complete, unreduced Social Security benefit. It is currently 67 for anyone born in 1960 or later.
Work credits
Units the Social Security Administration uses to measure your work history. You earn up to four credits per year, and most people need 40 total to qualify for retirement benefits.
AIME
Average Indexed Monthly Earnings, the figure the SSA calculates from your highest 35 years of inflation-adjusted wages. It forms the basis of your benefit calculation.
PIA
Primary Insurance Amount, the monthly benefit you would receive if you claimed exactly at your full retirement age. All other benefit amounts are calculated as a percentage of this figure.
Delayed retirement credits
Extra credit added to your benefit for each month you wait past your full retirement age to claim, up to age 70. This permanently increases your monthly payment.
Spousal benefit
A Social Security benefit available to a current or former spouse based on the worker's earnings record rather than the spouse's own record.
This article covers general educational information about Social Security. For guidance specific to your financial situation, consult a licensed financial adviser or contact the SSA directly.
How your benefit amount is calculated
The SSA calculates your benefit using your 35 highest-earning years, adjusted for inflation. If you worked fewer than 35 years, the missing years count as zero, which lowers your average.
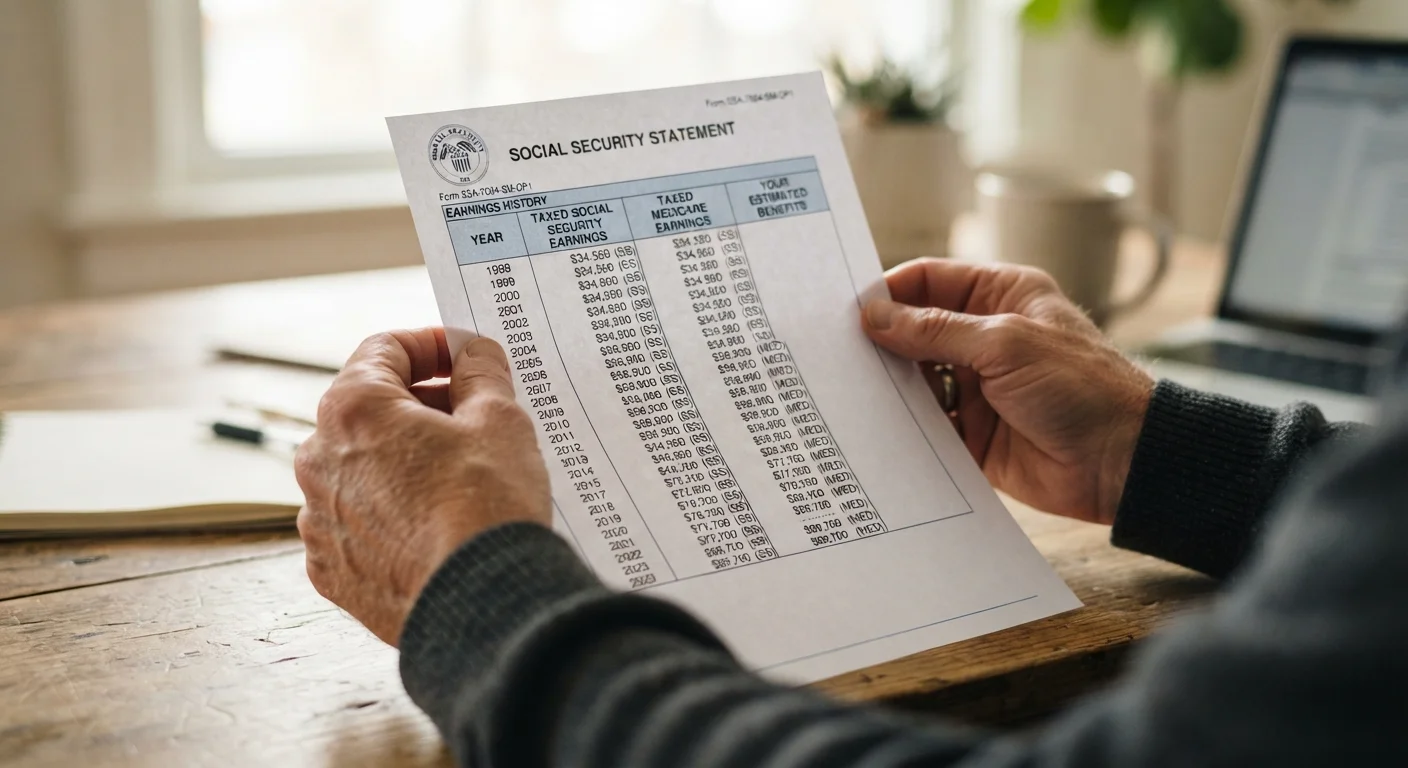
From those 35 years, the SSA derives your AIME and then applies a formula to produce your PIA. The formula is progressive, meaning lower earners receive a higher percentage of their average wages as a benefit. Higher earners receive more in dollar terms but a lower replacement rate.
Cost-of-living adjustments (COLA) are applied annually based on inflation, so your benefit is not frozen at the amount set when you first claim.
When you can start collecting
You have a window between age 62 and age 70 to begin collecting. The age you choose has a lasting effect on your monthly amount.
- Claiming at 62 permanently reduces your benefit, sometimes by 25 to 30 percent compared to your PIA.
- Claiming at your full retirement age (67 for those born in 1960 or later) means you receive your full PIA.
- Waiting past your FRA earns delayed retirement credits of 8 percent per year, up to age 70, permanently increasing your monthly payment.
Claiming early has permanent consequences
Reducing your benefit by claiming at 62 is not a temporary adjustment. The lower monthly amount applies for the rest of your life, including any cost-of-living adjustments calculated on top of it. Think carefully before claiming before your full retirement age.
For a detailed look at what these tradeoffs look like in dollar terms, see claiming Social Security early or late.
Spousal and survivor benefits
Social Security covers more than individual workers. A current spouse can receive up to 50 percent of the worker's PIA, provided the worker has already filed and the spouse is at least 62 (or any age if caring for a qualifying child).
A divorced spouse may also qualify if the marriage lasted at least 10 years and the divorced spouse has not remarried.
Survivor benefits apply when a worker dies. A surviving spouse who is at least 60, or 50 with a qualifying disability, may receive a benefit based on the deceased worker's record. The amount depends on the survivor's age at the time of claim and whether the worker had already filed.
These rules interact in ways that affect the best claiming strategy for married couples. Consulting a financial adviser who works with retirees can help you model different scenarios for your household.
What to do before you apply
A few concrete steps before your target claiming age can prevent problems and help you make a better-informed decision.
- Create a my Social Security account at ssa.gov and review your earnings record for accuracy.
- Check your estimated benefit at different ages using the SSA's Retirement Estimator tool.
- Confirm how Social Security income may interact with your other retirement income for tax purposes. See the overview of tax-advantaged accounts for context on how different income sources are treated.
- Apply up to four months before your intended start date. Online applications typically take less than 30 minutes.
Check your earnings record before you claim
Errors in your earnings history can lower your benefit permanently. Create a my Social Security account at ssa.gov to review your record and estimated amounts well before your target claiming age. Correcting a mistake takes time, so the sooner you check, the better.
Social Security and Medicare enrollment often overlap
Many people approaching retirement need to sort out both Social Security and Medicare at the same time. The two programs have separate enrollment windows and rules. See the Medicare enrollment checklist for guidance on that process.
This article is for general informational and educational purposes only. It is not financial, legal, or tax advice. Contact the Social Security Administration directly or consult a licensed professional for guidance specific to your situation.