How your claiming age changes your benefit
Your Social Security retirement benefit is calculated from your earnings record, but the age at which you file permanently adjusts that base amount. If you need a refresher on how the base calculation works, see Social Security Benefits: A First-Timer's Roadmap before reading further.
Filing before your full retirement age (FRA) reduces your monthly payment. Filing after your FRA increases it. The FRA sits at 66 for people born between 1943 and 1954, then rises by two months per birth year until it reaches 67 for everyone born in 1960 or later.
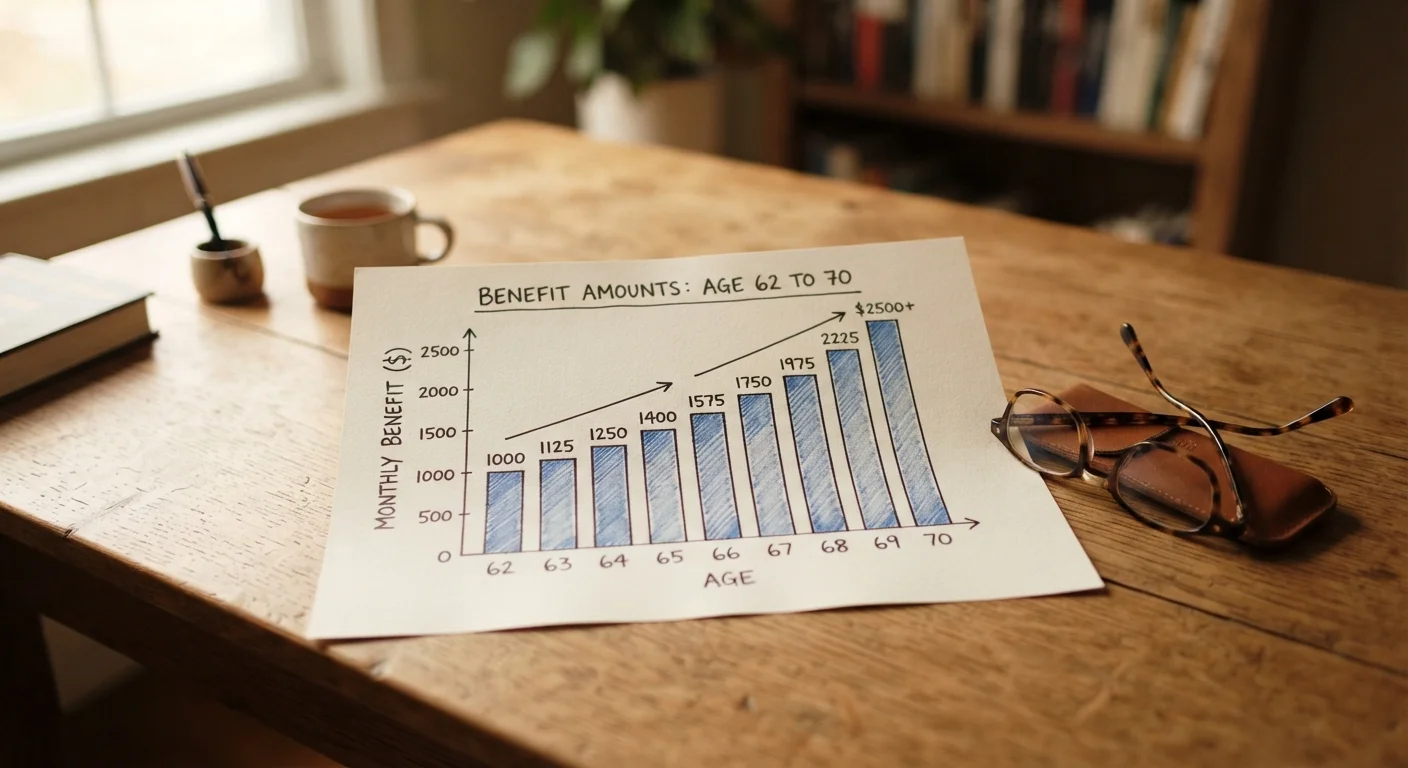
The Social Security Administration applies a reduction of 5/9 of one percent for each of the first 36 months you file early, and 5/12 of one percent for each additional month beyond that. At 62, someone whose FRA is 67 faces a 30 percent reduction. Conversely, delayed retirement credits add roughly 8 percent per year for each year you wait past your FRA, capped at age 70.
Pros and cons of claiming early
Claiming at 62 is the most common filing age, largely because it delivers income sooner. That has real value for people who leave the workforce early, whether by choice or necessity.
More years of receiving monthly payments
Claiming at 62 means you start collecting up to five years before your full retirement age, which can add up to a meaningful sum if you live an average lifespan.
Helpful if you have limited other income sources
For people who stop working early due to health or job loss, an early benefit can bridge a real income gap before other savings are drawn down.
Reduces need to withdraw retirement savings early
Receiving Social Security income can allow retirement accounts more time to grow, even if the benefit itself is reduced.
Significantly larger monthly checks at 70
Waiting until 70 can increase your benefit by as much as 32 percent above your full retirement age amount, which compounds across every cost-of-living adjustment.
Stronger spousal and survivor protection
A higher earner's larger benefit carries over to a surviving spouse, which can make a meaningful difference for the lower-earning partner's financial security.
Better hedge against a long retirement
If you live into your late 80s or 90s, the higher monthly benefit from delayed claiming tends to produce more lifetime income than early claiming.
The tradeoff is a smaller check that arrives for more years. Someone in poor health, with a family history of shorter lifespans, or with no other income source may reasonably conclude that early claiming fits their situation. This article provides general information, not personalized financial advice. A licensed financial adviser can help you model whether early filing makes sense for your household.
Early benefits are permanently reduced
Claiming at 62 can reduce your monthly benefit by up to 30 percent compared to your full retirement age amount, and that reduction does not go away over time.
Working while collecting early has income limits
Before you reach full retirement age, the Social Security Administration withholds part of your benefit if your earnings exceed an annual threshold, though those withheld amounts are later credited back.
Breakeven age may be beyond average life expectancy
If you claim early and live a shorter-than-average life, total lifetime benefits may exceed what you would have collected by waiting, but this calculation depends heavily on individual health.
Delaying requires sufficient income to cover the gap
Waiting until 70 only works if you have savings, a pension, or other income to cover living expenses from retirement until you file, which is not feasible for everyone.
No additional benefit to waiting past 70
Delayed retirement credits stop accruing at age 70, so there is no financial reason to postpone filing beyond that point.
Early claiming limits flexibility if circumstances change
Once you file, reversing the decision is possible only within 12 months and requires repaying all benefits received, a step most people cannot take.
The breakeven calculation
A breakeven analysis compares total lifetime benefits at different filing ages. The math is straightforward: divide the total additional income from waiting by the monthly difference in benefit amounts. That tells you roughly how many months you need to collect the higher benefit to recoup what you gave up by waiting.
For many people, the breakeven age lands somewhere in the late 70s. If you live past that point, waiting generally produces more total income. If not, early filing often wins on total dollars received. Health and family history matter here, but neither is a reliable predictor for any individual. Thinking through financial milestones across decades can also help frame how Social Security fits into broader retirement planning.
One-time do-over rule
If you claim early and change your mind, the Social Security Administration allows one withdrawal of your application within 12 months of filing. You must repay every dollar you received, including any benefits paid to family members on your record. After 12 months, suspension of benefits (not full withdrawal) is available starting at full retirement age, which stops payments but lets credits accumulate again.
Spousal and survivor benefit considerations
Married couples face a more complex decision because two benefit records interact. A spouse who earned less over a career may qualify for up to 50 percent of the higher earner's benefit at their FRA. If the higher earner delays to 70 and then dies first, the surviving spouse steps up to that larger amount for the rest of their life.
This dynamic often leads financial planners to suggest that the higher earner in a couple consider delaying, while the lower earner may claim earlier to bring in some household income. Coordination between two filing strategies can matter more than either decision in isolation. An SSA counselor or licensed adviser familiar with spousal claiming rules can walk through the specifics for your household. You may also want to understand how Medicare enrollment timing fits into this period; delaying Medicare enrollment can carry permanent costs that run alongside Social Security decisions.
This article is for general informational purposes only and does not constitute financial, legal, or tax advice. Consult a qualified financial adviser or the Social Security Administration directly for guidance specific to your situation.