The basic structure of an auto policy
An auto insurance policy is not one thing. It is several separate coverage types sold together. Each type covers a different scenario, carries its own limit, and may have its own deductible. Insurers present them as a package, but you are paying for each piece individually.
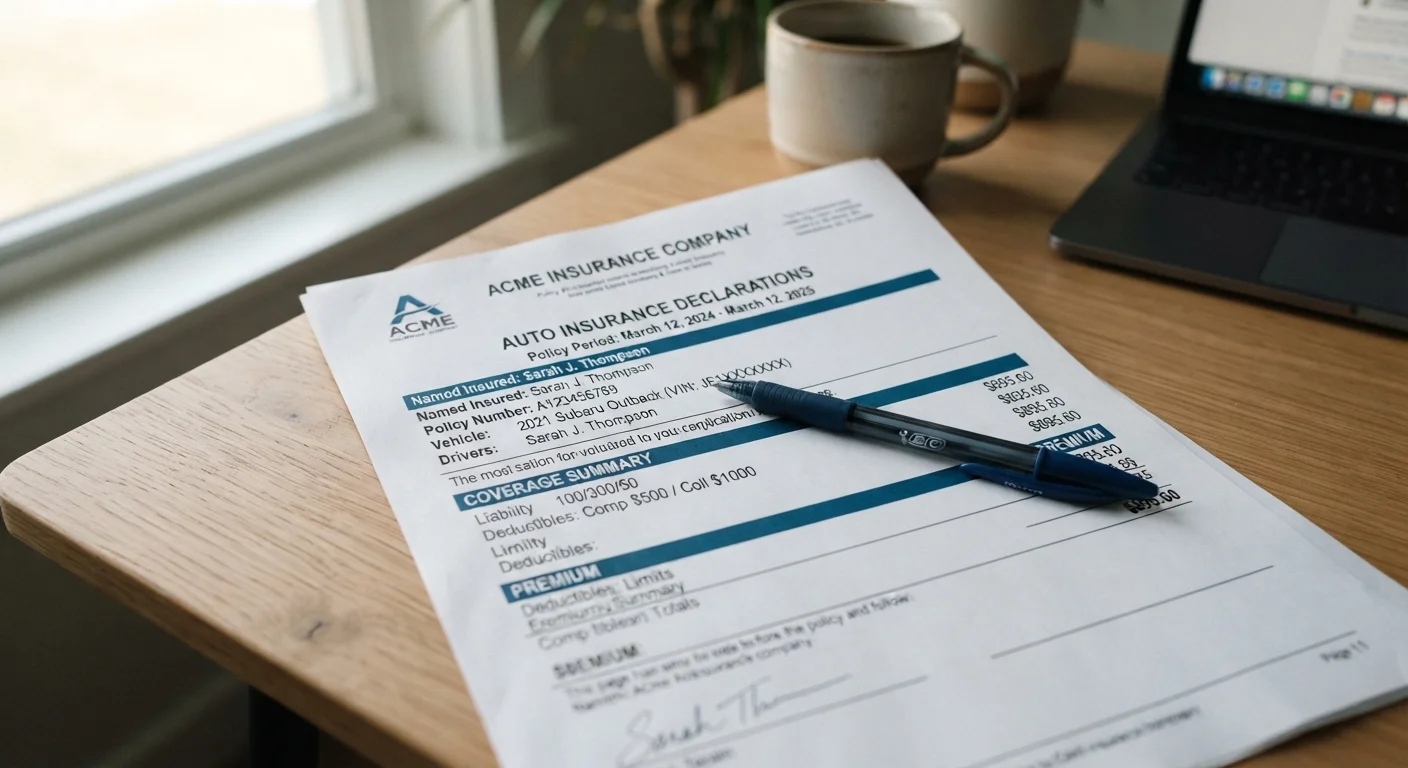
The declarations page, sometimes called the dec page, lists every coverage type you have, the dollar limit for each, and what deductible applies. If you have never read yours, that single page tells you more about your actual coverage than any marketing summary. See how to read a similar summary document in this guide to reading an insurance declarations page.
What liability coverage pays for
Liability is the coverage most people have heard of, and most states require at least a minimum amount. It pays for two things when you cause an accident: the medical bills of people you injure (bodily injury liability) and the repair or replacement cost of property you damage (property damage liability).
Liability does not pay anything toward your own vehicle or your own medical bills. Its purpose is to protect the other party and to protect you from a lawsuit exceeding what you can pay out of pocket.
State minimums are low in many cases. A single hospitalization can exceed a $25,000 bodily injury limit quickly. Choosing a higher limit costs more in premiums but reduces the risk that you owe money beyond what the policy covers.
State minimums are a floor, not a recommendation
Every state sets the lowest amount of liability coverage a driver must carry, but those floors were set years ago and have not kept pace with medical and repair costs. A serious accident can produce bills well above a state minimum limit. Choosing coverage above the minimum is a personal financial decision, not just a legal one.
Collision and comprehensive: your vehicle, two different situations
Collision coverage pays to repair or replace your vehicle when it is damaged in a crash, regardless of who caused it. If you hit another car, a guardrail, or a tree, collision is the coverage that applies to your car.
Comprehensive coverage handles losses that are not collisions: theft, fire, flood, hail, a falling branch, or hitting an animal. Many drivers think of it as everything-else coverage for their vehicle.
Both types pay up to the actual cash value of your car, not the purchase price. Actual cash value reflects depreciation, so an older vehicle may receive a much smaller payout than you expect. If you owe more on a loan than the car's current value, gap insurance covers that difference.
Coverage types you may not have thought about
Medical payments coverage (MedPay) and personal injury protection (PIP) both pay for medical expenses after an accident regardless of fault. PIP is broader in most states and can cover lost wages and rehabilitation costs. Some states require PIP; others do not offer it.
Uninsured and underinsured motorist coverage pays when the other driver has no insurance or not enough to cover your losses. The Insurance Research Council has estimated that roughly one in eight drivers in the U.S. is uninsured, so this coverage addresses a real and common gap.
Rental reimbursement and roadside assistance are optional add-ons. They cost relatively little but apply only in narrow situations. Know what you have before you assume they are included.
Review your policy before you need it
Pull out your declarations page once a year and confirm that the limits you have still match your situation. If your car's value has dropped significantly, adjusting collision or comprehensive coverage may make sense. A licensed agent can walk you through what each change would mean for your premium and your protection.
How deductibles and limits affect what you actually pay
Two numbers on your policy shape your real financial exposure: the deductible and the coverage limit. The deductible is what you pay first on a covered claim. The limit is the ceiling above which the insurer stops paying.
A $500 deductible on collision means a $1,200 repair costs you $500 and the insurer pays $700. A $1,000 deductible on the same repair costs you $1,000 and the insurer pays $200. Higher deductibles lower your premium but raise your out-of-pocket cost per claim.
Coverage limits work the same way in reverse. A $50,000 property damage liability limit means your insurer pays up to $50,000 in damage you cause. If the actual damage is $80,000, you owe the $30,000 gap. This interaction between limits and real-world costs is why reading your dec page matters more than accepting default numbers.
For drivers new to all of this, this practical starting guide for first-time car owners walks through coverage decisions step by step. And if you have heard things about auto insurance that seem off, common myths versus the facts is worth checking.
This article is for general informational purposes only and is not personalized insurance or legal advice. Coverage types, requirements, and terms vary by state and insurer. Read your policy documents carefully and consult a licensed insurance agent for guidance specific to your situation.