What the 50/30/20 rule actually says
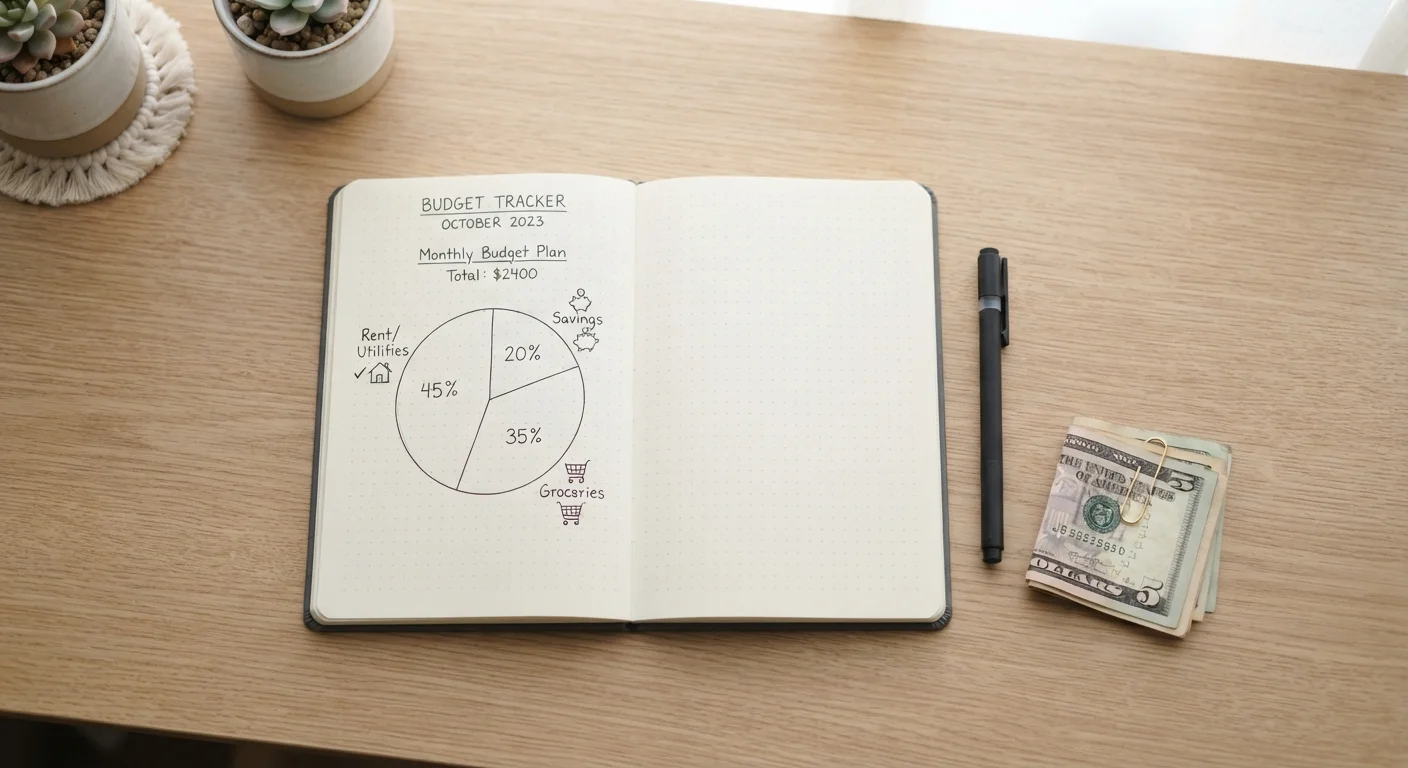
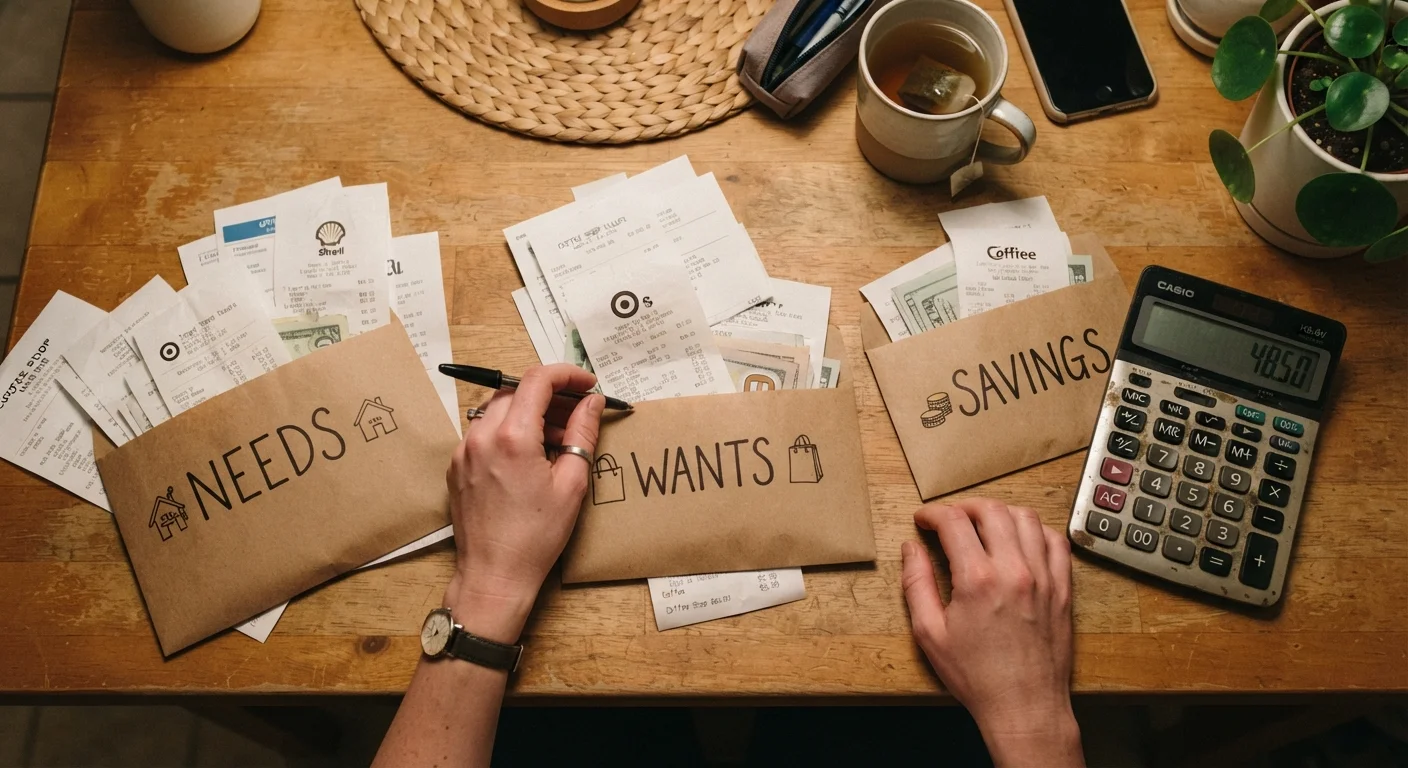
The 50/30/20 framework divides monthly after-tax income into three buckets. Fifty percent goes toward needs: housing, utilities, groceries, health insurance, and minimum loan payments. Thirty percent goes toward wants: dining out, streaming services, hobbies, and similar discretionary spending. Twenty percent goes toward savings and extra debt repayment, covering emergency funds, retirement accounts, and paying down balances faster than the minimum requires.
The rule is sometimes attributed to the approach popularized in the 2005 book All Your Worth by Elizabeth Warren and Amelia Warren Tyagi, though percentage-based budgeting existed in personal finance circles well before that. Its appeal is clarity: three numbers, applied once a month, tell you whether your spending is broadly on track.
Understanding the core components of a personal budget is useful context before applying any percentage-based system, because the categories only work if you have an accurate picture of what you actually spend.
Where the framework works well
For someone with a steady paycheck, moderate housing costs, and no major debt burden, the 50/30/20 split is a functional starting point. It does not demand a detailed spending log, and it produces a savings habit without requiring the person to decide each month how much to set aside.
Simple enough to start immediately
The framework requires no spreadsheet expertise. Anyone who knows their monthly take-home pay can divide it into three categories within minutes, which lowers the barrier for people who have never budgeted before.
Gives every dollar a category without micromanaging
Unlike line-item budgets that track every subscription and grocery receipt, the 50/30/20 method groups spending broadly. That reduces the administrative burden that causes many people to abandon detailed budgets after a few weeks.
Built-in savings allocation
By hardwiring 20% for savings and debt repayment, the framework makes saving a default rather than an afterthought. That structure can help people who tend to save whatever is left over at month end, which is often nothing.
Easy to recalibrate as income changes
Because the categories are percentages rather than fixed dollar amounts, the plan scales with income. A raise or a cut in hours shifts the dollar amounts automatically without requiring a full budget rebuild.
The framework also adapts reasonably well to life changes. Financial milestones shift across your 30s, 40s, and 50s, and a percentage-based plan moves with income in a way that fixed dollar targets do not.
Where the framework breaks down
The rule's fixed percentages assume a particular relationship between income and cost of living that does not apply universally. Several structural problems limit how well it works in real households.
50% needs ceiling is unrealistic in high-cost cities
In metro areas where median rent alone can consume 40% or more of a moderate income, fitting housing, utilities, groceries, insurance, and transportation into 50% is not achievable for many households. The framework does not offer guidance on what to cut when needs exceed the ceiling.
Not designed for low incomes
When take-home pay is small, basic needs frequently exceed 50% of income no matter how carefully someone shops. Applying a framework built around discretionary spending to a household that has little discretionary spending can produce guilt without producing a workable plan.
Blends very different savings goals into one bucket
The 20% category covers emergency funds, retirement contributions, and debt payoff without distinction. Someone aggressively paying off high-interest debt while contributing nothing to retirement may hit 20% on paper while still falling behind on long-term financial health.
The needs vs. wants line is genuinely ambiguous
A car payment is a need for someone with no transit options and a want for someone with reliable public transportation. The framework gives no decision rule for these gray areas, so two people in similar situations can categorize spending very differently and reach very different conclusions about their finances.
Ignores existing debt loads
A household carrying significant student loans, medical debt, or credit card balances may need to direct far more than 20% toward debt repayment to make meaningful progress. The standard split can create a false sense of progress if minimum payments absorb most of the 20%.
This article is general financial information
The 50/30/20 rule is one budgeting framework among several. Nothing in this article is personalized financial advice. Your income, debt, housing costs, and long-term goals are individual factors that a licensed financial adviser or certified financial planner can help you weigh.
Adjusting the rule to fit your situation
Financial planners often describe the 50/30/20 split as a starting reference rather than a hard target. If your housing costs push needs past 60%, the practical response is to compress the wants category temporarily rather than to treat the plan as broken. If you carry high-interest debt, directing more than 20% toward payoff while reducing discretionary spending is often a sounder approach than maintaining the standard split.
Common patterns that derail savings goals often trace back to plans that were too rigid to survive an unexpected expense or a change in income. A budget that bends deliberately is more durable than one that snaps the first time reality does not match the formula.
If you are planning a large trip, similar proportional thinking applies. Budgeting a U.S. road trip involves the same principle of deciding in advance how much each category of spending can absorb before you commit.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Consult a licensed financial professional for guidance tailored to your circumstances.