How to calculate your net worth
The math is straightforward. Add up the current value of everything you own: checking and savings account balances, retirement account balances, investment accounts, the market value of any real estate you own, vehicle values, and any other property worth converting to cash. That total is your assets.
Next, add up everything you owe: mortgage balance, car loans, student loans, credit card balances, personal loans, and any other outstanding debts. That total is your liabilities.
Subtract liabilities from assets. The result is your net worth.
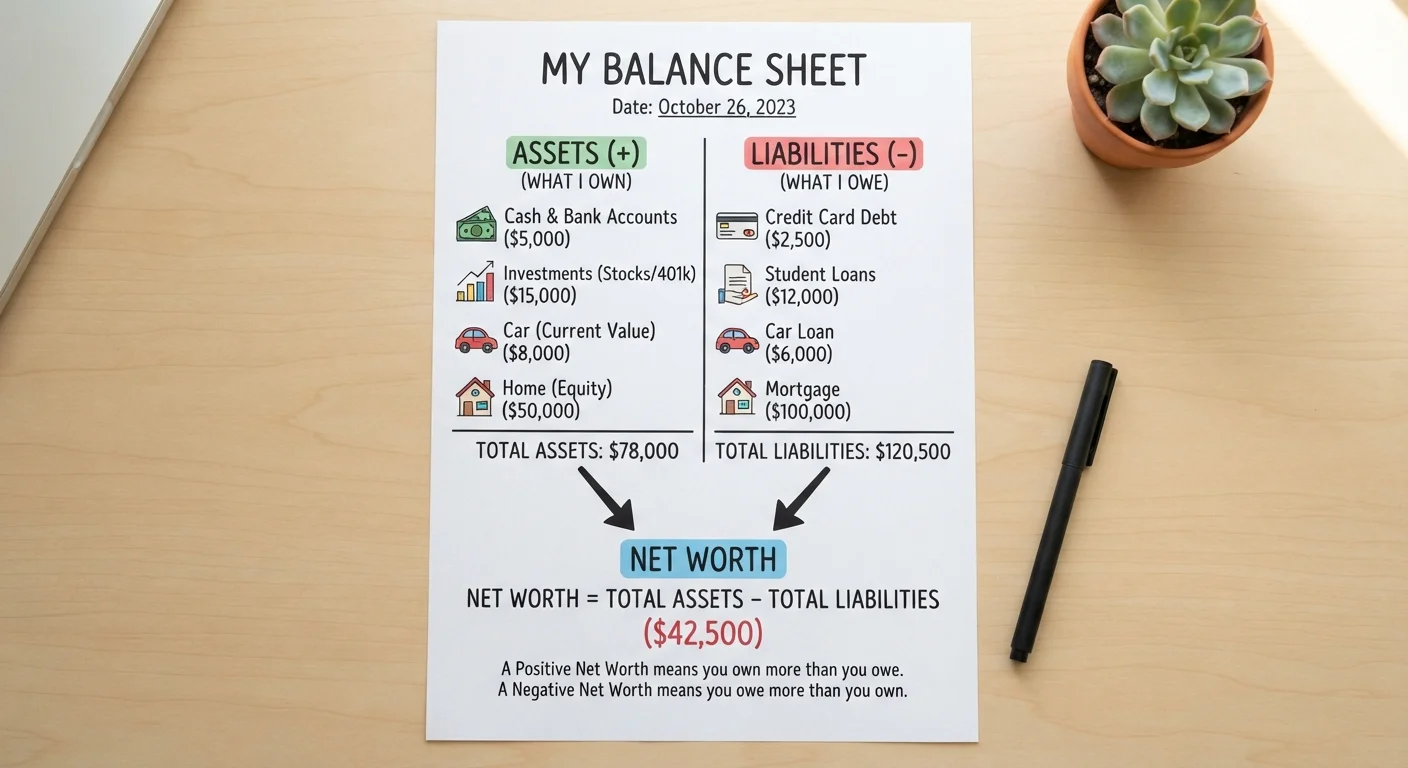
A few practical notes. Use current market value for assets, not what you paid. Home values change, and so do investment balances. For debts, use the current payoff balance, not the original loan amount. Updating these figures once or twice a year keeps your number meaningful.
If you want a foundation for budgeting that complements this exercise, the building blocks of a personal budget covers how to structure your monthly income and spending alongside your balance sheet.
What net worth actually tells you
Net worth is a snapshot of accumulated financial position. It does not measure income, spending habits, or cash flow directly. Two people with the same monthly salary can have very different net worths depending on how long they have been saving, how much debt they carry, and what assets they have built.
The number is most useful as a trend line. A net worth that grows steadily over several years shows that assets are accumulating faster than debt. A flat or declining net worth, even with a rising income, can signal that spending or debt levels deserve a closer look.
Start with a simple spreadsheet
You do not need specialized software to track net worth. A two-column spreadsheet listing assets and liabilities, updated twice a year, is enough to spot meaningful trends. Many free budgeting tools also include a net worth tracker built in.
Net worth also helps you see concentration risk. If nearly all your net worth sits in one asset, such as home equity, your financial position is less flexible than the headline number suggests. Liquid assets, those you can access without selling property or triggering penalties, matter separately.
This article is for general informational purposes only and does not constitute personalized financial, investment, tax, or legal advice. Consult a qualified, licensed financial professional before making decisions based on your own financial situation.
Common assets and liabilities people overlook
People often undercount assets by forgetting smaller accounts: a Health Savings Account (HSA), a cash-value life insurance policy, or a vehicle that still holds meaningful resale value. On the liability side, informal debts owed to family members or a deferred tax bill on a traditional IRA are real obligations even if no monthly statement arrives.
Some items are worth noting separately rather than blending into the total. The balance in a 401(k) is technically an asset, but accessing it before retirement age typically triggers income taxes and a 10% penalty. That means the accessible value is less than the statement shows. A realistic net worth calculation acknowledges that difference.
$192,700
Median U.S. household net worth
According to the Federal Reserve's 2022 Survey of Consumer Finances, the median net worth for all U.S. families was $192,700.
$1,063,700
Mean U.S. household net worth
The same Federal Reserve survey reported a mean (average) net worth of $1,063,700, which reflects how high-wealth households pull the average far above the median.
Recurring insurance costs can also affect the pace at which net worth grows. Understanding what you are paying for coverage, whether that is home, auto, or life insurance, helps clarify how much of your income goes toward protection versus saving. For auto coverage specifically, auto insurance explained breaks down what each coverage type actually does.