Refinancing a loan can change your monthly picture, but the decision involves more than just a lower rate. Work through this checklist before moving forward.
Key Takeaways
A lower interest rate does not automatically mean refinancing saves you money overall.
Your credit score and debt-to-income ratio affect the rate a lender will actually offer you.
Closing costs on a refinance typically range from 2% to 5% of the loan amount.
The break-even point tells you how long you need to stay in the loan to recover upfront costs.
Extending your loan term can lower monthly payments while increasing total interest paid.
Consulting a licensed financial adviser helps match the decision to your specific situation.
Why these questions matter before you apply
Refinancing replaces your current loan with a new one, usually with different terms. The appeal is often a lower interest rate or a reduced monthly payment. But a refinance also resets the clock on your loan and typically comes with closing costs that you either pay upfront or roll into the new balance. Working through a structured set of questions before you apply helps you figure out whether a refinance fits your financial situation, not just whether a rate looks attractive on paper.
This checklist is general financial information and not personalized advice. For guidance specific to your circumstances, consult a licensed financial adviser or mortgage professional.
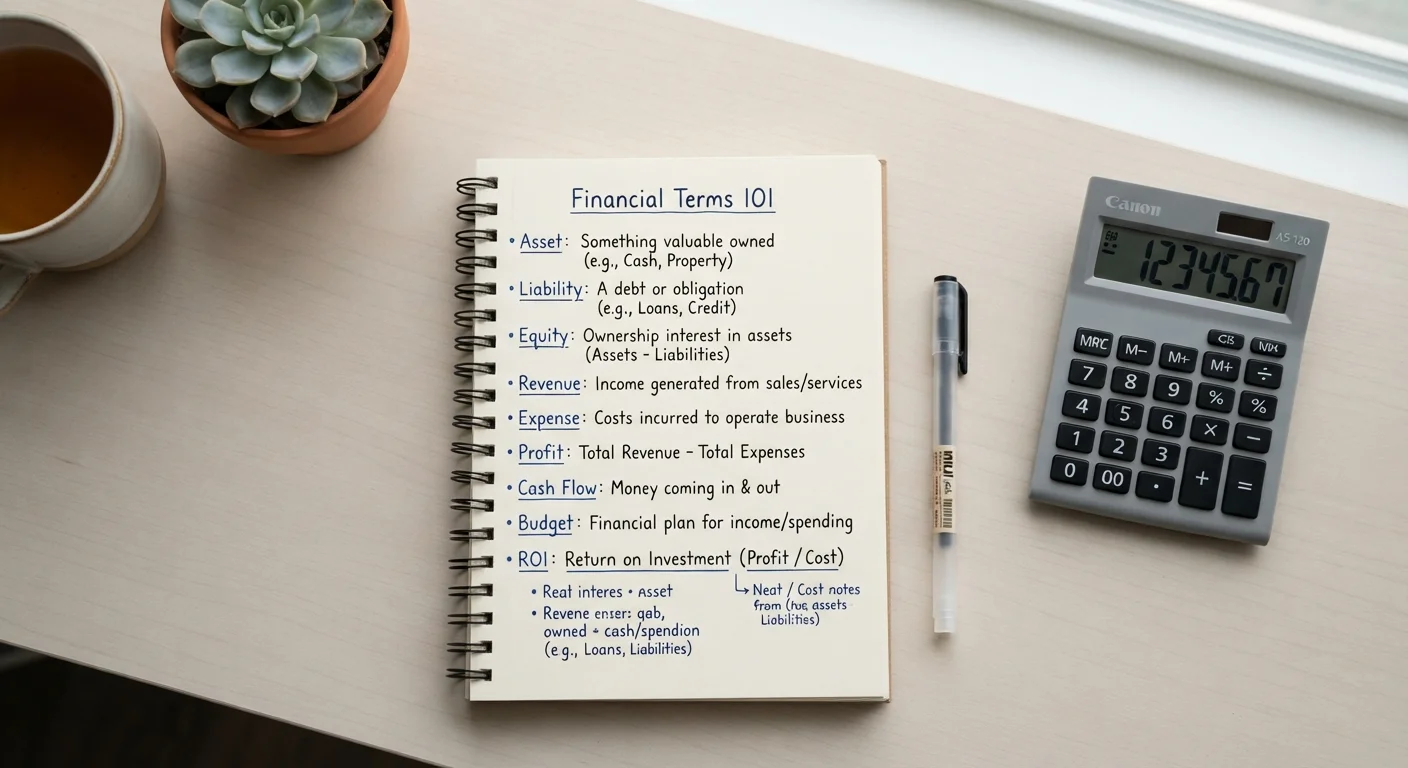
If any of the terms below are unfamiliar, the plain-language finance glossary covers concepts such as APR, amortization, and debt-to-income ratio.
Before you start: gather what you need
Having the right documents and figures on hand makes the checklist faster and more accurate.
Required
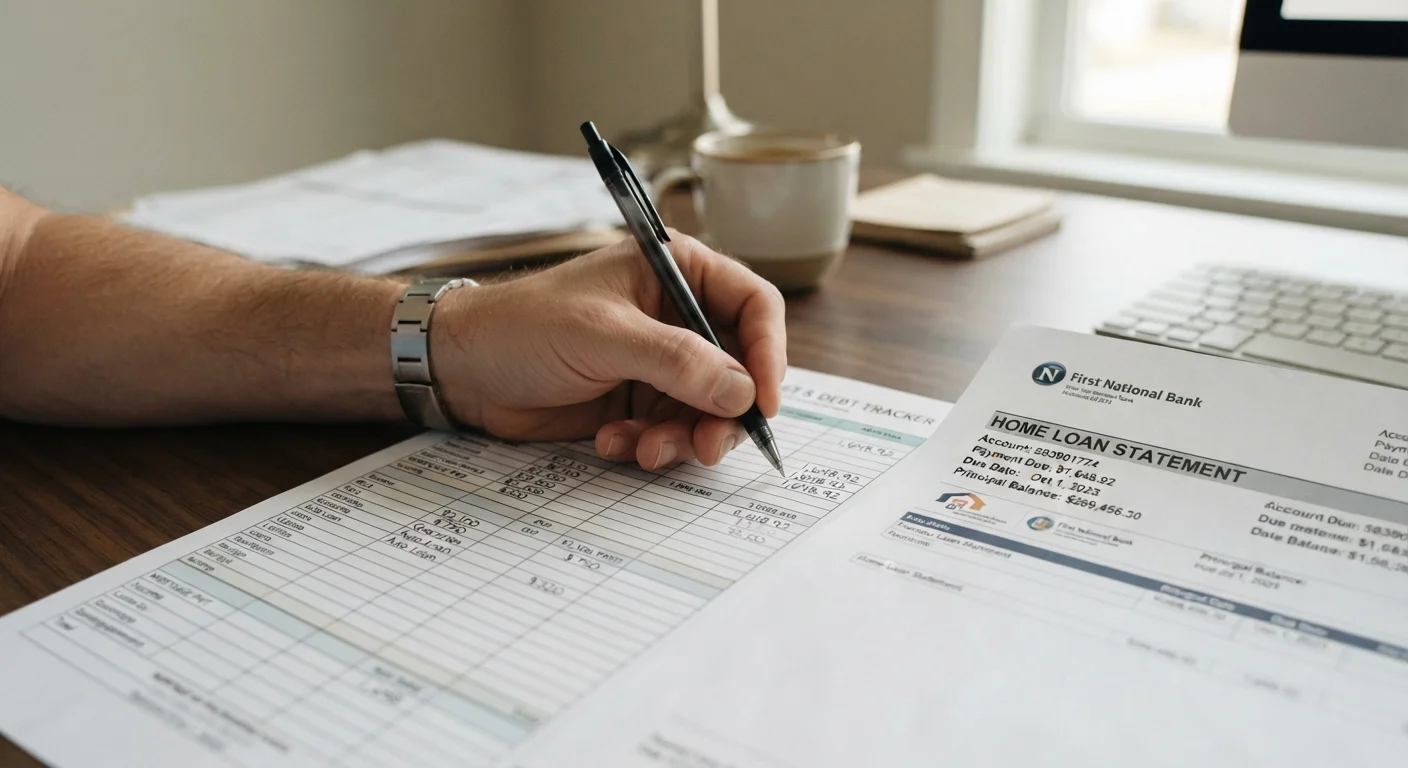
Current loan statement
Provides your exact remaining balance, interest rate, monthly payment, and payoff date.
Required
Recent pay stubs or income documentation
Lenders verify income during underwriting; having these ready speeds the process.
Required
Credit report
Shows your current credit score and any errors that could affect the rate you are offered.
Required
Amortization calculator
Computes total interest paid over the life of a loan under different rate and term scenarios.
Required
Loan Estimate forms from lenders
Federal form that standardizes cost and rate disclosures so you can compare offers on equal terms.
Questions to work through
Running your own numbers before you apply gives you a clearer picture of what a refinance will actually cost.
Your current loan
Pull your most recent loan statement and write down your current interest rate, remaining balance, monthly payment, and how many months are left on the loan.Must
Calculate the total interest you would pay if you made every remaining payment as scheduled. Your lender or an online amortization calculator can produce this figure.Must
Check whether your current loan has a prepayment penalty. Some loans charge a fee if you pay off the balance early, which a refinance would trigger.Must
Your financial profile
Get your credit score from a free annual credit report or your bank's credit monitoring tool before you approach any lender.Must
Calculate your debt-to-income ratio (DTI): add up your monthly debt payments, divide by your gross monthly income, and express the result as a percentage. Lenders generally prefer a DTI below 43%.Must
Review your employment history for the past two years. Most lenders require documented, stable income before approving a refinance.Should
The potential new loan
Get rate quotes from more than one lender so you have a real comparison, not just a headline figure from an advertisement.Must
Ask each lender for a Loan Estimate form, which breaks down rate, closing costs, and monthly payment in a standardized format required by federal law.Must
Confirm whether the quoted rate is fixed or adjustable. An adjustable rate can change after an initial period, which affects long-term planning.Must
The cost calculation
Total the closing costs for the new loan. These typically include origination fees, appraisal, title search, and recording fees, and often run 2% to 5% of the loan amount.Must
Calculate your break-even point: divide total closing costs by your monthly payment savings. The result is the number of months you need to keep the loan before the refinance pays for itself.Must
Decide whether you plan to be in this loan past the break-even point. If you expect to sell, move, or pay off the loan before that date, the savings may not materialize.Must
If you plan to roll closing costs into the new loan balance, recalculate your total interest cost with that higher principal before deciding.Should
Consider the impact on your tax situation if you currently deduct mortgage interest. Tax rules change, and a licensed tax professional can clarify how a refinance may affect your deductions.Should
A note on timing and loan length
One of the less obvious factors in a refinance decision is how the new loan term interacts with your current payoff timeline. If you have 18 years left on a 30-year mortgage and you refinance into a new 30-year loan at a lower rate, your monthly payment may drop, but you will be making payments for 12 more years than your original schedule. Over that extended period, total interest paid can exceed what you would have paid by staying in your current loan.
A shorter loan term, such as refinancing from 30 years to 15 years, usually carries a lower interest rate and builds equity faster, but the monthly payment will be higher. Neither path is universally better; the right choice depends on your cash flow, remaining loan balance, and how long you plan to stay in the home or hold the asset.
Extending your term raises total interest cost
A longer repayment term lowers the monthly payment but increases the total interest you pay over the life of the loan. Before accepting a new 30-year term on a loan you have already been repaying for several years, calculate the full interest cost of each scenario side by side. The monthly savings may look attractive while the lifetime cost is higher than your current loan.
The same framework that applies to mortgage refinancing also applies to auto loans and personal loans, though the numbers and timelines differ. If you own a home and are weighing renovation financing alongside a refinance, the homeowner maintenance guide covers how upkeep costs factor into long-term ownership expenses.
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.